All Categories
Featured


Benefits of IUL for Retirement
As you compare Medicare Supplement insurance strategies, think of how much treatment you require, how often you go to the doctor and just how much you can afford to pay towards your medical bills yourself. Each Medigap strategy has a different level of coverage, so you need to find one that fits your specific needs.
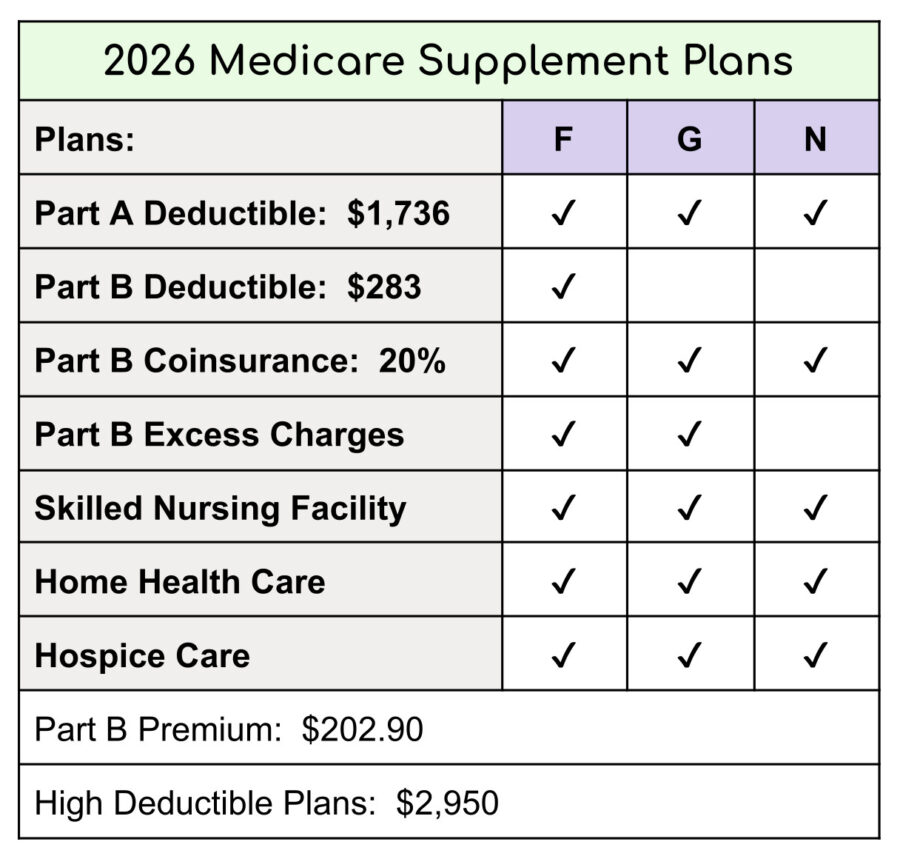
With Initial Medicare (Components A and B), you're accountable for paying roughly 20% of your health center bills. Medigap prepares pay for some or all of your staying costs, depending on your strategy letter. The best Medicare Supplement strategy for you depends on your health and spending plan. Leading strategies Part A coinsurance Yes Yes Yes Part B coinsurance Yes Yes Yes Blood transfer (3 pints) Yes Yes Yes Part A hospice care Yes Yes Yes Experienced nursing facility Yes Yes Yes Part A deductible Yes Yes Yes Part B deductible Yes Part B excess charges Yes Yes Yes = 100% Other plans Part A coinsurance Yes Yes Yes Yes Yes Yes Yes Part B coinsurance Yes Yes Yes Yes 50%75% Yes Blood (3 pints) Yes Yes Yes Yes 50%75% Yes Part A hospice care Yes Yes Yes Yes 50%75% Yes Knowledgeable nursing center Yes Yes 50%75% Yes Part A deductible Yes Yes Yes 50%75%50%Part B deductible Yes Part B excess chargesForeign travel emergency80%80%80% Yes = 100% This can offer you assurance since you will not be surprised by high medical expenses.
Plans F and C have better protection than Strategy G, however you can't get them if you're a new enrollee. If you purchase a strategy with low coverage when you're 65 and later on decide to update to something much better, such as Plan G, companies might quote you a high rate or reject you coverage entirely.
Plan G has the very best coverage for many seniors and others on Medicare. After you pay this, Plan G will pay for treatment such as doctor sees, blood tests or outpatient medical treatment. Pros and cons of Strategy G Popular plan that covers nearly all of your health expenses Often a better worth than Plan F Rates can be expensive, at $180 each month, on average Less expensive plans might be a better offer if you seldom visit the doctor Strategy F has the finest protection of any Medigap strategy in general.
Pros and cons of Strategy F Spends for nearly all medical expenses High monthly rates Not readily available to brand-new Medicare enrollees Strategy N has comparable protection to Plan G but costs less. With Strategy N, you need to pay $20 for doctor gos to and $50 for trips to the emergency situation room.
Insurance in Stanton CAWhy Veterans Choose Burial Insurance Protection
Benefits and drawbacks of Plan N Yes Covers nearly all of the costs you're responsible for with Medicare Yes Strategy N costs about $137 each month, which is $43 per month less than Plan G Bonus costs you are accountable for paying when you visit the doctor could counteract cost savings You might have additional costs if your medical professional does not accept the rates set by Medicare High-deductible Strategy G has the cheapest regular monthly rate of any Medigap policy.
Keep in mind, companies can charge higher rates or reject coverage due to the fact that of your health history if you alter Medicare Supplement plans outside the 6 months around your 65th birthday. That means you may be stuck to a high-deductible Plan G when you're older and in worse health, costing you more in the long run.

This indicates that Medicare Supplement Plan G from AARP/UnitedHealthcare provides you the very same coverage as Strategy G from Aetna, Blue Cross or any other business.

Latest Posts
Benefits of IUL for Retirement
Vital Health Coverage Strategies
Enhancing Long-Term Security with Whole Life Insurance